

I’ve dug into the details of the One Big Beautiful Bill Act (OBBBA) so you don’t have to. I’ve pulled out the 10 most important things you should know about how and when your taxes might change. There’s even a hidden gem just for military spouses (!!!). Here’s a quick look at what might matter most to you. As always, I’m here to help you figure out how it all fits your personal financial plan.
1. Tax Brackets [2025] Are Now Permanent
Permanent means “not expected to change”. While the tax brackets were expected to change at the end of 2025 and now they are not, I think it is safe to assume that they will change at least as often as the legislators change. So, permanent should be a flexible term. These brackets are nearly the same following OBBBA, but you could see a slight reduction in your effective tax rate due to a very slight change in the lower tax thresholds.
2. Higher Standard Deductions
The standard deduction is getting a boost:
- Single: $15,750 [2025]
- Head of Household: $23,625 [2025]
- Married Filing Jointly: $31,500 [2025]
- Seniors (65+)*: additional $6,000 ($12,000 for joint filers if both are 65+) [2025-28]
*There is an income phaseout for this deduction (see chart below).
NOTE: It was rumored (because the Social Security Administration sent out an email that said as much) that Social Security would not be taxed thanks to OBBBA. This is false, though this deduction may offset some of those taxes for some filers.
3. Child Tax Credit* Increased and Indexed for Inflation
- [2025] $2,200
*There is an income phaseout for this deduction (see chart below).
4. Estate Tax Exemption Increased
- [2026] $15 million per person, $30 million per couple
5. 529 Plan Flexibility
529 plans were already one of my favorite education planning tools, but OBBBA has created more opportunities to use it with a broader definition of qualified education expenses. It now includes:
- Expanded list of K-12 expenses [2025]
- K-12 Distribution up to $20,000 [2026]
- Post-secondary credential expenses [2025]
Reviewing the Benefits of the 529 Savings Plan
6. Repeal of Clean Energy Credits
- Clean Vehicle [expires 9/30/2025]
- Electric Vehicle Charging Equipment [expires 6/30/2026]
- Energy Efficiency Home Improvement [expires 12/31/2025]
- Residential Clean Energy [expires 12/31/2025]
7. Changes to Itemized Deductions
If you itemize, pay attention to these updates:
- State and Local Tax (SALT) Deduction* [2025]
- Deduction limit increased to $40,000
- Less relevant to Florida residents (thanks to no state tax)
- Less relevant to disabled veterans who benefit from reduced property taxes
- Mortgage Insurance Premiums are deductible again [2026]
- Based on the fact that VA funding fees were deductible as Private Mortgage Insurance (PMI) in the past, and because the new law doesn’t state otherwise, I believe that it wi’ll also be deductible.
NOTE: If you are financing a VA home loan, you should bring this to the attention of your accountant
- Charitable Contributions subject to new 0.5%-of-Adjusted Gross Income (AGI) floor [2026]
- high income taxpayers might want to make contributions in 2025 before the new floor takes effect
NOTE: this is different than the Below The Line WITH A TWIST Deduction mentioned below
- Casualty Losses [2026]
- Rule loosened from ONLY federally declared disaster to include state declared disasters
- Miscellaneous Deductions eliminated and Educator Expenses added
- They have to itemize to use it
- Section 199A Deduction extended for Business Owners
8. Above the Line, Below the Line & Below the Line WITH A TWIST
Let’s clear up some tax lingo because OBBBA adds a new twist to tax planning.
Above the line deductions are subtracted from your income before your Adjusted Gross Income (AGI) is calculated. This helps lower your AGI, which can be important for things like qualifying for tax credits or reducing how much of your Social Security is taxed. Anyone who qualifies can use these deductions.
Below the line deductions come after AGI is figured out. They still lower your taxable income, but they don’t affect AGI. You can only use these if you itemize your deductions instead of taking the standard deduction—and they only help if your itemized total is higher than the standard deduction.
But OBBBA introduces a new twist:
You get “below-the-line-style” deductions WHILE TAKING the standard deduction:
- That $6,000 for taxpayers 65+* I mentioned previously is below the line with a twist
- $1,000 for charitable contributions ($2,000 for married filers)
- Cash only
- Not subject to the new 0.5% floor
- New deductions for:
✔️ Tips* (up to $25,000 with a phaseout)
✔️ Overtime* (up to $12,500 with a phaseout)
✔️ Auto Loan Interest*
*There is an income phaseout for these deductions (see chart below).
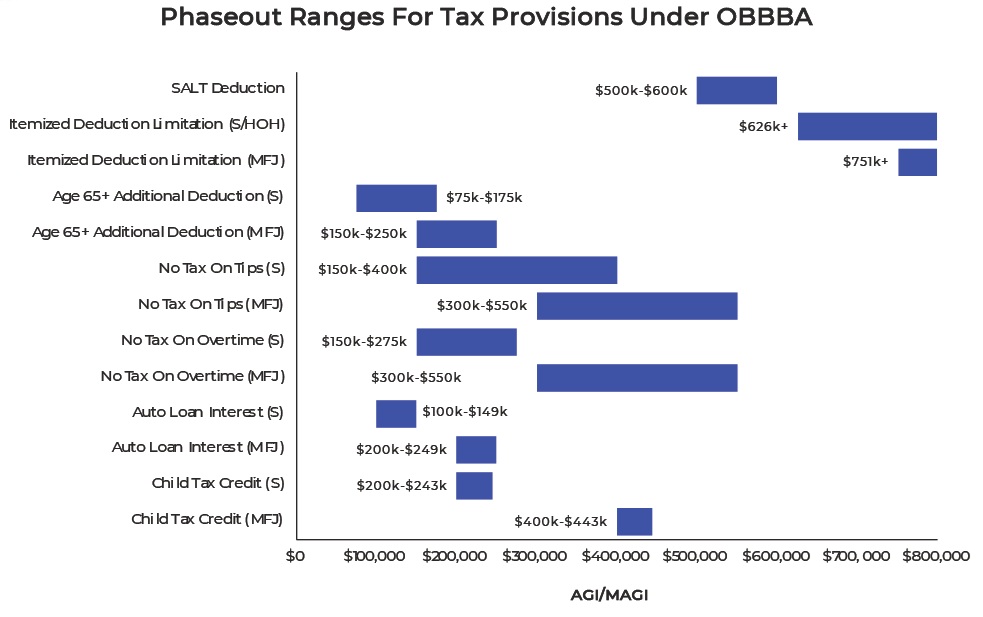
Chart adapted from Kitces.com, Breaking Down the “One Big Beautiful Bill Act”, July 2024.
9. “Trump Accounts”: A New Kind of Savings Tool
These new tax-advantaged accounts are like IRAs for kids. I’m a fan of saving and investing early, so I like the idea. Details are still rolling out for these accounts that will be available in [2026], but here’s what I know:
- No earned income requirement (like current IRAs)
- Contributions are not tax deductible (like Roth IRAs)
- $5K annual limit (per contributor per beneficiary)
- Contributions are excluded from beneficiaries income – good come FAFSA time
- Limited to US equities index
- Fees no higher than 0.1% (good, I like low fees)
- No distribution until beneficiary is >18 (except to rollover to 529 ABLE)
- Once 18, rules are similar to Traditional IRA; unclear about investment options, rollovers, Roth conversions, RMDs, etc. > 18
- Pilot program for US citizens born in 2025-27; $1,000 paid by US gov’t
These could be powerful tools for the next generation.
10. Military Spouse Licensure
Buried in OBBBA is a powerful win for military families. Under Section 20001, Congress allocated $10 million to the Department of Defense specifically to support military spouses who must transfer professional licenses when they relocate due to a Permanent Change of Station (PCS). This is new funding not a renewal or a patchwork solution.
Whew! That was a lot! Just imagine having to actually deal with the actual bill! But not to worry . . . that’s what I’m here for; to help you make good decisions that align your goals with the opportunities that align with them (like me shopping for new windows to beat the expiration of that tax deduction).
If you’d like to review your current strategy or talk through any questions, schedule a call with me.
BayView Financial Planning [BFP] is a Registered Investment Adviser in the state of Florida. Advisory services are only offered to clients or prospective clients where BFP and its representatives are properly registered or exempt from registration. “Likes” should not be considered a positive reflection of the investment advisory services offered by BFP.
Stacy Miller, CFP® is an investment adviser representative of BayView Financial Planning. The firm is a registered investment adviser and only conducts business in jurisdictions where it is properly registered, or is excluded or exempted from registration requirements. Registration as an investment adviser is not an endorsement of the firm by securities regulators and does not mean the adviser has achieved a specific level of skill or ability.
The information presented on this post is believed to be factual and up-to-date, but we do not guarantee its accuracy and it should not be regarded as a complete analysis of the subjects discussed. Comments should not be construed as an offer to buy or sell, or a solicitation of an offer to buy or sell the investments mentioned. A professional adviser should be consulted before implementing any of the strategies discussed. Investments involve varying degrees of risk, and there can be no assurance that any specific investment or strategy will be suitable or profitable for a client’s portfolio. All investment strategies can result in profit or loss.